There is a dangerous misconception shared by thousands of condominium and HOA residents across Palm Beach and Martin County: "If a Category 3 hurricane blows our community's roofs off, our association's master property insurance policy will pay to replace them." In reality, understanding how an HOA master insurance hurricane roof deductible operates under Florida Statute § 718.111(11) is a sobering wake-up call for every board treasurer and unit owner in South Florida.
Because master commercial property insurance valuations (Total Insured Value, or TIV) have surged by 40% to 70% over the past four years—and because most South Florida associations now carry a 3%, 5%, or even 10% Per-Building Hurricane Deductible—an association with $40 million in insured buildings can face a $2,000,000 out-of-pocket deductible gap after a single named windstorm! Here is how the math works and how proactive roof hardening protects your community from post-hurricane financial insolvency.
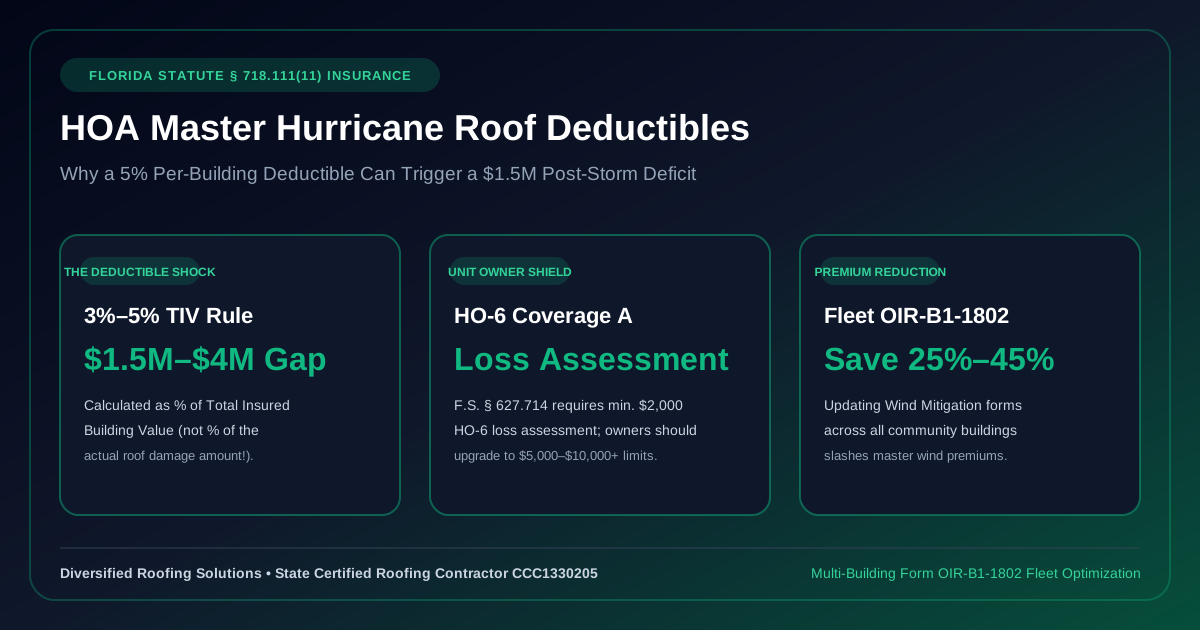
An HOA master insurance hurricane roof deductible in Florida (typically 2% to 5%+) is calculated as a percentage of each building’s Total Insured Replacement Value (TIV)—not the cost of the roof damage. Under a Per-Building Hurricane Deductible, a storm can inflict $1,000,000+ in roof damage across a 25-building HOA while resulting in a $0 insurance payout if no individual building’s roof damage exceeds its 5% building deductible threshold.
Mandates that the association carry primary replacement-cost property insurance on all roofs and building exteriors outside the unit drywall, while classifying any unpaid master hurricane policy deductible as a mandatory common expense funded by reserves or special assessment against all unit owners.
The "Per-Building Deductible" Trap: A Real-World South Florida Example
To see why so many HOA and condominium boards in Jupiter, Boca Raton, West Palm Beach, and Stuart get blindsided after a hurricane, walk through this exact mathematical scenario:
- The Community: A 20-building garden-style condominium or townhome HOA in Palm Beach County.
- Insured Building Value (TIV): Each 8-unit building has a replacement cost valuation of $2,500,000 ($50,000,000 Total Insured Value across all 20 buildings).
- Master Policy Hurricane Deductible: 5% Per-Building Calendar-Year Hurricane Deductible (= $125,000 deductible per individual building; $2,500,000 total exposure).
- The Storm Event: A Category 2 hurricane strikes Palm Beach County. High winds tear off ridge caps, crack 35% of the concrete tiles, and cause active leaks on all 20 buildings. Each building requires a complete $110,000 roof replacement ($2,200,000 total roof replacement bill across the 20 buildings).
- The Insurance Payout: $0.00! Because each building's $110,000 roof replacement cost falls just below that specific building's $125,000 (5% of $2.5M) Per-Building Deductible, the master insurer owes zero dollars—leaving the HOA board to assess unit owners for the entire $2.2 million!
Comparing HOA Master Policy Deductible & Roof Risk Structures
| Policy / Roof Condition Scenario | Typical Master Hurricane Deductible | Deductible Dollar Exposure ($30M TIV Community) | Annual Master Premium Impact |
|---|---|---|---|
| Roofs Over 18–20 Yrs Old (Surplus Lines / Layered) | 5% – 10% Per Building (Plus ACV Roof Endorsement!) | $1,500,000 – $3,000,000 out-of-pocket exposure | Highest Premium (Often 2x standard rates) |
| Roofs 10–15 Yrs Old (Outdated OIR-B1-1802 Forms) | 3% – 5% Per Building | $900,000 – $1,500,000 out-of-pocket exposure | Overpaying by 20%–35% due to missing wind credits |
| New FBC Roofs + SWR + Updated Fleet OIR-B1-1802 | Eligible for 2% – 3% Calendar-Year with preferred carriers | $600,000 – $900,000 (and roofs survive 170+ MPH winds!) | Saves 25% – 45% Every Year on master policy |
Watch Out for "Actual Cash Value (ACV) Roof Schedule" Endorsements!
Beyond the HOA master insurance hurricane roof deductible, check your association's policy binder for a silent killer known as a "Roof Surface Payment Schedule" or "Actual Cash Value (ACV) Roof Endorsement."
If your community's shingle roofs are over 12–15 years old or your tile/flat roofs are over 18–20 years old, surplus lines carriers increasingly slip an ACV endorsement onto the policy. Under an ACV schedule, even if a tornado or Category 4 hurricane completely destroys a 20-year-old roof, the insurer depreciates the roof by 60% to 80% first—and then subtracts your 5% hurricane deductible on top of that!
3 Action Steps for Every Florida HOA & Condo Board Today
- Audit Your Fleet of Form OIR-B1-1802 Wind Mitigation Reports: In a 25-building community, every single residential building requires its own current Uniform Mitigation Verification Inspection Form (OIR-B1-1802) signed within the last 5 years. Have our licensed inspectors audit your buildings and run your community's numbers on our Florida Wind Mitigation Insurance Savings Calculator.
- Establish a Dedicated Catastrophe Deductible Line of Credit: Before June 1st (Hurricane Season), work with your association's bank to establish a standby emergency line of credit or HOA roof financing plan sized to cover your hurricane deductible.
- Educate Unit Owners on HO-6 Loss Assessment Endorsements: Send an annual newsletter reminding unit owners to ask their personal HO-6 insurance agent to increase their Loss Assessment Coverage above the statutory $2,000 minimum (F.S. § 627.714) and confirm whether their carrier caps hurricane deductible assessments.
Need a master-policy roof life expectancy certification or multi-building wind mitigation audit? Contact Diversified Roofing Solutions' HOA & commercial roofing team today.