Over the past 24 months, hundreds of thousands of South Florida homeowners have opened their mailboxes to find a mandatory Citizens insurance depopulation roof and policy assumption notice. As Florida's state-backed insurer of last resort aggressively shrinks its policy count, private "takeout" carriers—such as Slide Insurance, Monarch National, Loggerhead, SafePoint, and Manatee—are assuming policies across Palm Beach, Martin, Broward, and St. Lucie counties.
While the state legislature designed depopulation to reduce taxpayers' hurricane assessment risk, many homeowners are caught off guard by what happens after their policy transfers to a private company. Navigating Citizens insurance depopulation roof underwriting requires understanding the statutory "20% Rule," how private insurers use AI-driven aerial imagery to flag older roofs, and how to prevent a surprise non-renewal notice at your first private renewal.
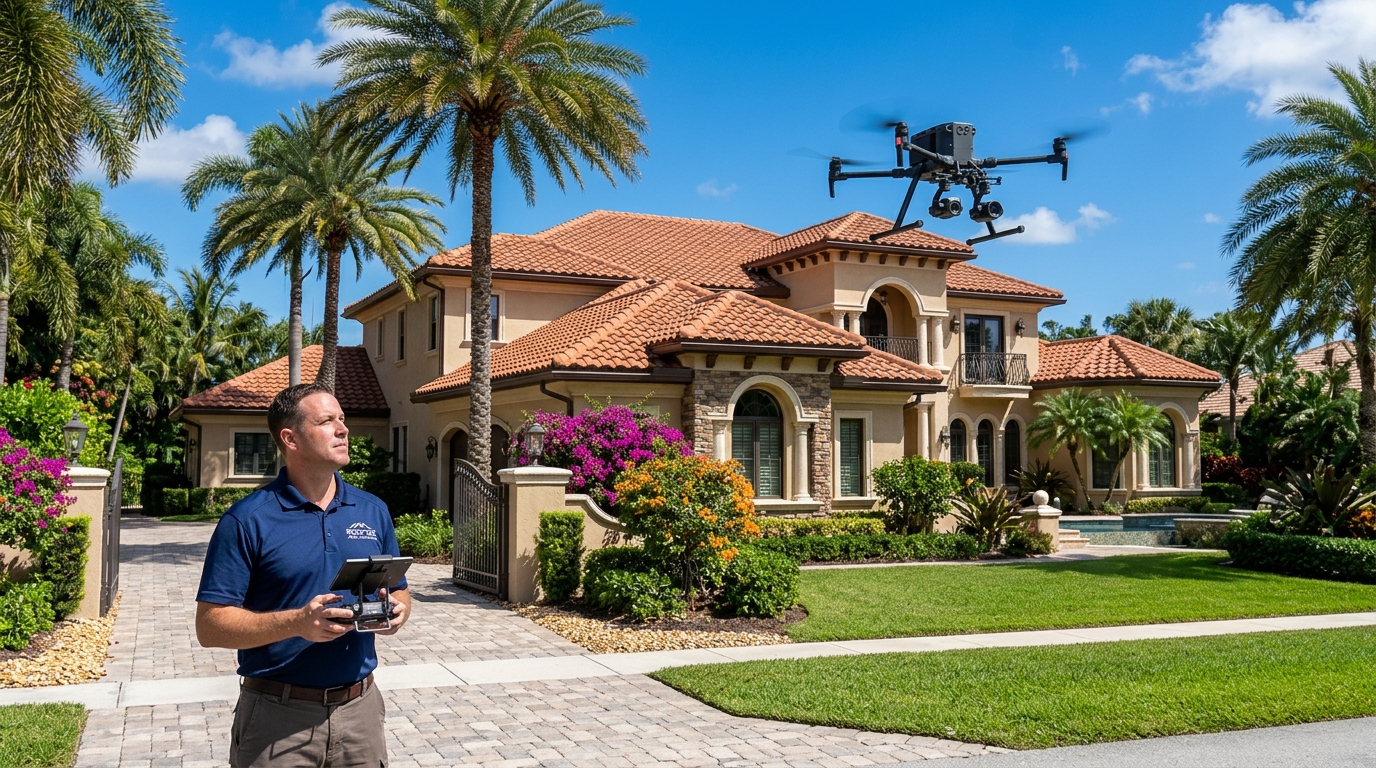
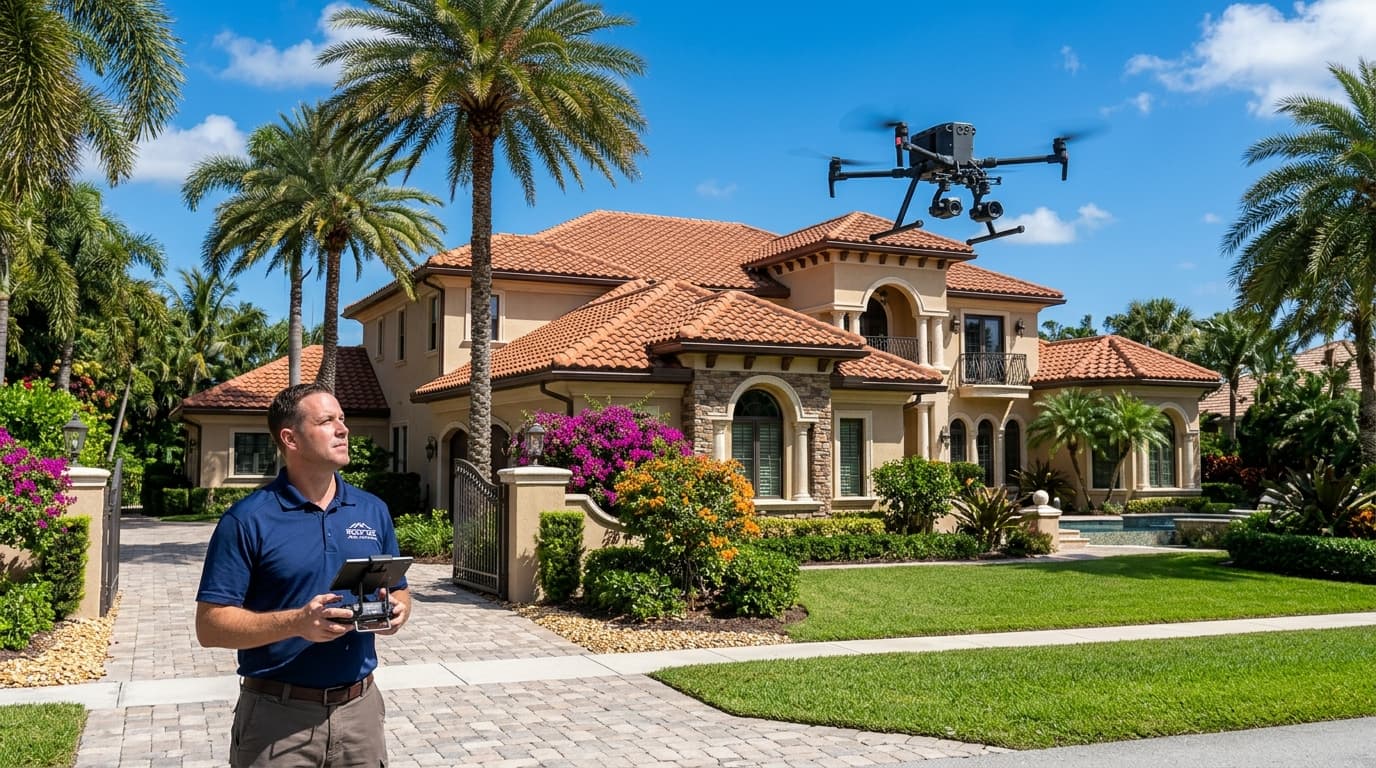
Under Florida’s Citizens Depopulation Program (F.S. § 627.351), if a private takeout insurer offers coverage within 20% of your Citizens renewal premium, you are legally required to leave Citizens. Because private takeout carriers utilize high-resolution aerial imagery to scrutinize roof condition before your next renewal, homeowners with shingle roofs over 12 years old or tile roofs over 20 years old should proactively secure a state-certified Remaining Useful Life (RUL) inspection and updated OIR-B1-1802 Wind Mitigation report.
Establishes the mandatory 20% takeout eligibility threshold for Citizens policyholders while prohibiting residential property insurers from refusing to issue or renew a policy solely due to roof age if the roof is under 15 years old or certified by an authorized inspector to have at least 5 years of remaining useful life.
How the Citizens "20% Rule" Impacts South Florida Homeowners
In previous years, if Citizens sent you a depopulation takeout notice, you could simply submit an "Opt-Out" form and stay with Citizens regardless of price. Under the reforms enacted in Senate Bill 2-A, that opt-out privilege was eliminated whenever a takeout carrier's offer falls within 20% of your estimated Citizens renewal premium.
For a homeowner in Jupiter, Wellington, or Stuart paying $5,500 per year with Citizens, a private carrier offering a policy at $6,550 (+19.1%) triggers mandatory depopulation. Even if you ignore the letter, your policy is automatically transferred on the assumption date.

Why Takeout Carriers Scrutinize Your Roof More Strictly
Once a private insurer assumes your policy, they inherit your current Citizens policy terms until your next renewal date. However, during the 60 to 90 days leading up to that first private renewal, takeout carriers run automated underwriting audits:
- AI Satellite & Airplane Overflight Scans: Private carriers subscribe to quarterly aerial photography databases (such as Nearmap and Verisk/Geomni). Computer-vision algorithms scan your rooftop for dark Gloeocapsa magma algae staining, mismatched repair tiles, rusted valley flashing, ponding water on low-slope patio decks, and tree limbs overhanging the roof plane.
- Tile Underlayment Age Audits: Even if your concrete or clay barrel tiles in Boca Raton or Palm Beach Gardens look intact from the street, private underwriters look up the municipal building permit history. If the roof permit is 20 to 23 years old and still relies on original 30-lb organic felt underlayment, the carrier may demand a fresh Roof Condition Certification Form prior to renewal.
- Strict Enforcement of F.S. § 627.7011(5): For roofs 15 years or older, Florida law requires the insurer to allow the homeowner to obtain an inspection at the homeowner's expense before requiring a roof replacement as a condition of renewal. If the inspection certifies 5 or more years of Remaining Useful Life (RUL), the carrier cannot non-renew solely for roof age.
Citizens vs. Private Takeout Carrier Roof Underwriting Comparison
| Underwriting Metric | Citizens Property Insurance | Private Takeout Carriers (Slide, Monarch, etc.) | Best Homeowner Action Step |
|---|---|---|---|
| Asphalt Shingle Roof Age | 15+ years requires RUL inspection showing $ge$ 3–5 yrs life | Strictly audited at renewal; aerial scans flag granule loss at yr 12+ | Schedule a proactive certified roof inspection before renewal |
| Concrete & Clay Tile Roofs | 25–30+ years scrutinized for underlayment dry-rot | Often require clean attic & tile inspection at 20+ years | Consider a tile roof lift and relay to reset RUL to 25+ yrs |
| Aerial / Drone Photo Audits | Periodic underwriting reviews | Automated AI scans for tree overhang, algae, & patched valleys | Trim branches 6+ ft back and fix cracked tiles immediately |
| Wind Mitigation Credits | Standard OIR-B1-1802 actuarial table | Higher base wind premium means OIR-B1-1802 credits save more $ | Calculate your credits on our Wind Mitigation Calculator |
4 Proactive Steps to Take When You Receive a Depopulation Letter
If you receive a Citizens Notice of Assumption and Offer of Coverage, do not wait until 30 days before your policy expires to verify your roof's compliance:
- 1. Eliminate Aerial Underwriting Red Flags Immediately: Trim all oak, palm, and mahogany branches back at least 6 to 10 feet from your roofline. Replace any cracked hip, ridge, or field tiles using a licensed contractor so satellite overflights show a pristine, well-maintained roof surface.
- 2. Secure a State-Certified Roof Condition Inspection: Have a Florida State Certified Roofing Contractor (CCC1330205) inspect both your exterior roof covering and your interior attic decking. If your roof is between 15 and 22 years old and structurally sound with zero active leaks, an official RUL certification protects your legal right to renewal under F.S. § 627.7011.
- 3. Audit Your Form OIR-B1-1802 Wind Mitigation Report: Because a private takeout carrier can charge up to 20% more than Citizens, every wind mitigation checkbox becomes 20% more valuable. Verify whether your attic has hurricane clips or single wraps, and check if adding a third nail or upgrading your roof covering can cut your new private premium by $1,800 to $3,500 per year.
- 4. Leverage My Safe Florida Home Grants If Your Roof Is Near End-of-Life: If your shingle roof is 17 years old or your tile underlayment is deteriorating, explore our My Safe Florida Home grant guide or run an instant estimate on our Roofing Cost Calculator to replace your roof before a non-renewal notice forces you into a rushed timeline.