Receiving a Florida roof insurance claim denial after tropical force winds or a severe squall line batters your home is one of the most frustrating experiences a property owner can face. Across Palm Beach County and Martin County, thousands of homeowners who faithfully pay $6,000 to $14,000 annually in property insurance premiums open letters from their carrier stating that their leaking roof, cracked barrel tiles, or creased architectural shingles were caused by "wear and tear, thermal expansion, or installation defects"—or that the covered damage falls below their hurricane deductible.
Understanding how to challenge and overturn a Florida roof insurance claim denial requires moving beyond emotional frustration and responding with hard engineering data, statutory building code citations, and forensic documentation. When an insurance desk adjuster reviews a file, they only reverse a denial or approve a full replacement when presented with indisputable physical proof that sudden wind uplift compromised the watertight envelope.
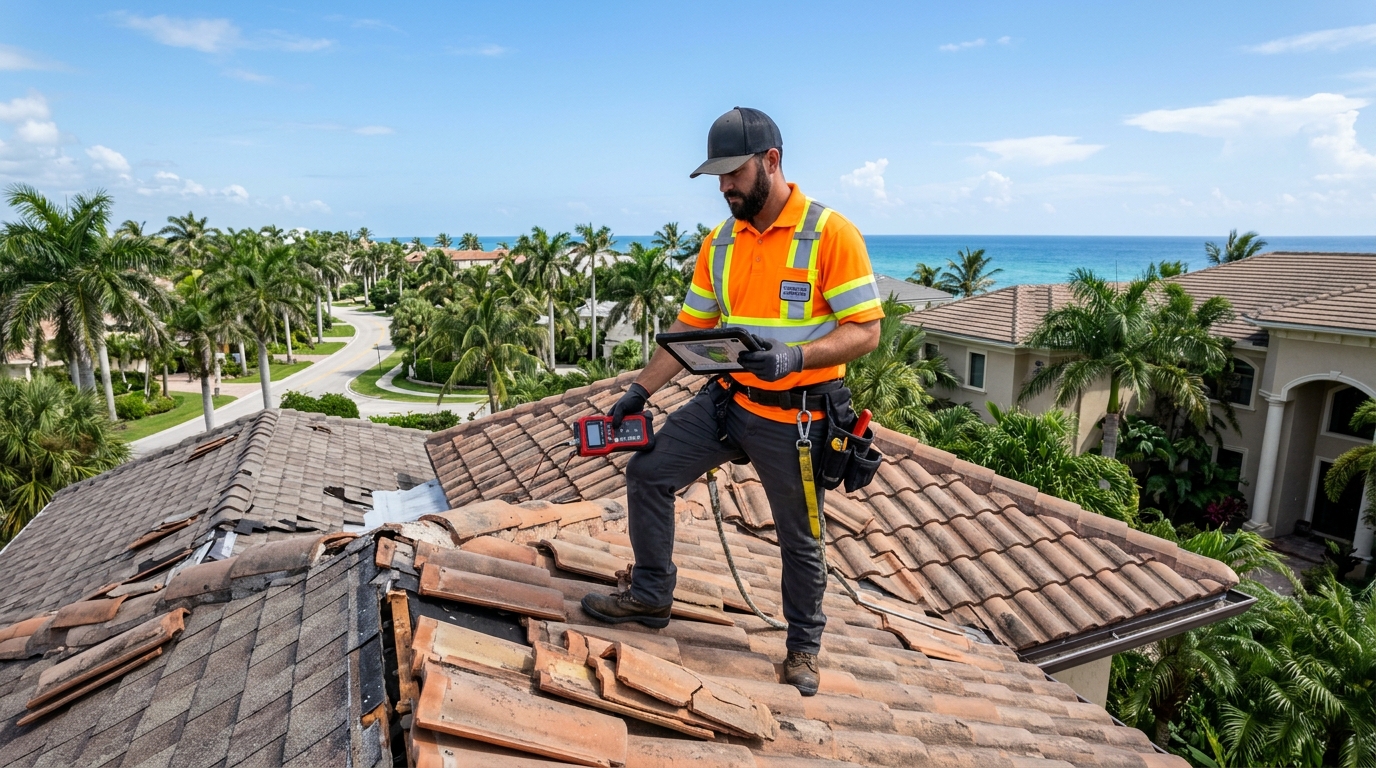
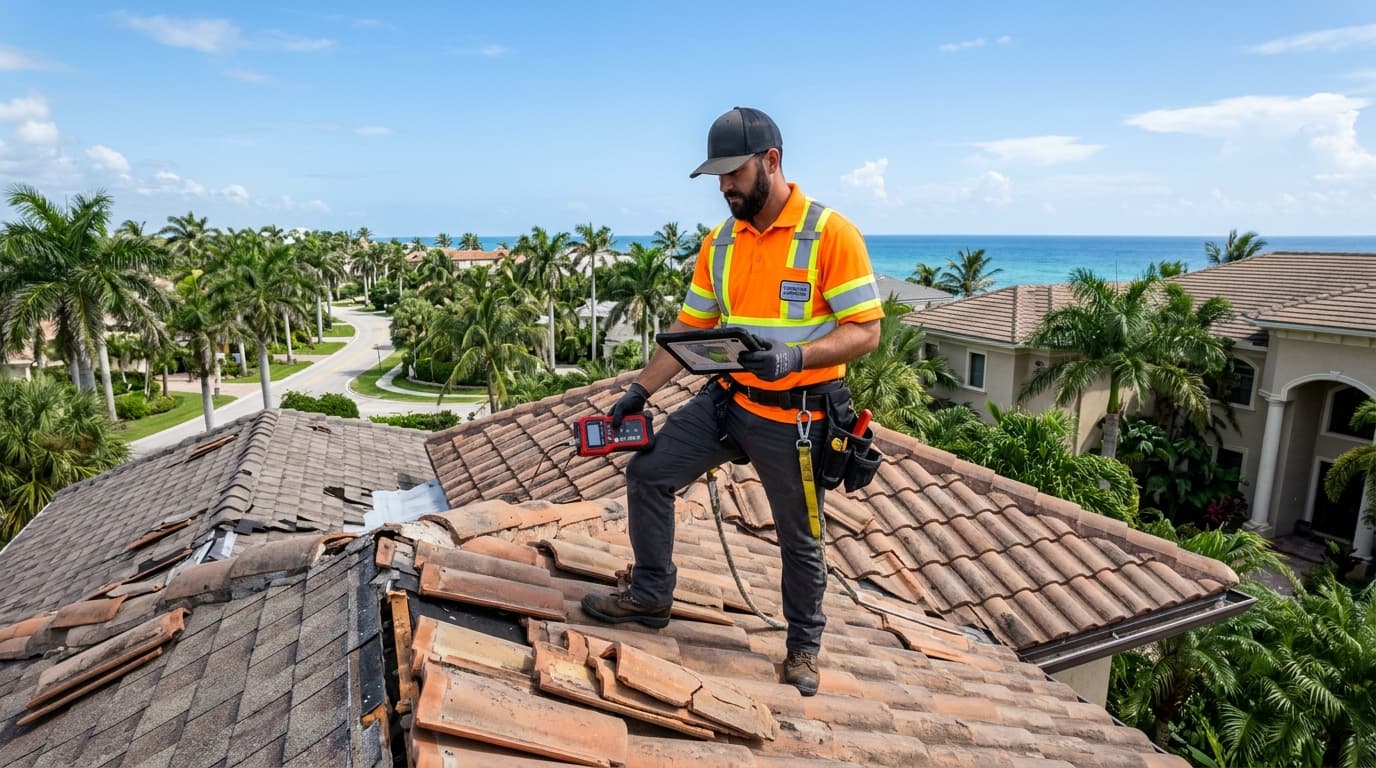
A Florida roof insurance claim denial is most commonly triggered when field adjusters classify storm uplift as routine wear and tear or estimate repair costs below your hurricane deductible. Homeowners can overturn denials by commissioning a forensic inspection from a Florida State Certified Roofing Contractor (CCC1330205) to document mat fractures, discontinued tile profiles, infrared moisture intrusion, and mandatory Florida Building Code upgrade requirements under F.S. § 627.70131.
Mandates strict 7-day acknowledgment, 30-day physical inspection, and 60-day claim determination timelines for residential property insurers, while requiring all roof repairs to conform to current High-Velocity Hurricane Zone (HVHZ) and wind-borne debris region building codes.
The 4 Most Common Reasons for a Florida Roof Insurance Claim Denial
When insurance carriers dispatch third-party ladder-assist inspectors following a storm in Jupiter, Palm Beach Gardens, or Stuart, those inspectors are trained to separate sudden accidental wind damage from long-term weathering. The four primary denial classifications include:
- 1. "Wear, Tear, and Deterioration" Exclusions: Carriers frequently claim that unsealed asphalt shingles or slipped concrete tiles failed due to UV aging or mortar breakdown rather than wind gusts. However, sudden wind uplift leaves distinct physical signatures—such as clean fiberglass mat creases on the top surface of shingles or freshly sheared mechanical fastener holes in tile battens.
- 2. "Foot Traffic vs. Wind Impact" on Tile Roofs: On concrete and clay barrel tile roofs in gated communities like Admirals Cove or PGA National, field adjusters often label right-angle corner breaks as "maintenance foot traffic." Forensic analysis distinguishes wind-borne debris fractures and uplift chattering from compression breaks by examining the fracture propagation vector and sub-tile underlayment tears.
- 3. Under-Deductible Partial Repair Estimates: Instead of issuing an outright Florida roof insurance claim denial, a carrier may acknowledge 12 damaged tiles or 20 blown-off shingles and price the repair at $1,800—well below a typical 2% or 5% Florida hurricane deductible ($8,000 to $25,000). They omit the fact that the existing tile profile is discontinued or that neighboring shingles cannot be lifted without tearing brittle, aged sealant strips.
- 4. "No Storm-Created Opening" for Interior Water Damage: Many Florida policies contain an endorsement excluding interior ceiling and drywall water damage unless wind or hail first creates a physical opening in the roof cover or exterior wall. Proving that wind-driven rain entered through lifted flashing, torn ridge vents, or punctured underlayment is essential to unlocking coverage.

Forensic Evidence Required to Overturn a Denied Roof Claim
To successfully reverse a Florida roof insurance claim denial, your appeal package must provide objective engineering proof that satisfies the carrier's desk examiner or state mediator:
| Carrier Denial Reason | Forensic Counter-Evidence Required | Governing Code / Technical Standard | Typical Claim Outcome Impact |
|---|---|---|---|
| "Shingles only need spot patching" | Documented Repairability / Brittle Test video showing adjacent tabs fracturing when lifted 45° for nail placement | FBC Existing Building § 706.1 (Repairs must not damage adjacent materials) | Converts spot patch into full slope or full roof replacement |
| "Concrete tiles can be individually swapped" | Official ITM / Tile Institute report proving the interlocking lug profile is obsolete and lacks a current Florida Product Approval (NOA) | FBC § 1507.3 & TAS 101/102 (Interlocking channel water-shedding integrity) | Forces batten-up replacement or tile roof lift and relay |
| "No evidence of active moisture intrusion" | Sunset radiometric infrared thermography scan + digital capacitance moisture meter readings of wet wood decking | ASTM C1153 & FBC § 706.3.1 (Prohibits trapping wet insulation or rotted sheathing) | Proves sudden storm breach of the secondary water barrier |
| "Damage occurred outside policy period" | Certified NOAA / NWS meteorological wind-swath verification correlated with unoxidized wood/fiberglass fracture surfaces | Florida Statute § 627.70132 (1-year new claim / 18-month supplemental filing window) | Establishes exact date-of-loss causation |
Step-by-Step Playbook: Appealing a Florida Roof Insurance Claim Denial
If your carrier denies your claim or sends an under-deductible settlement letter, follow this structured escalation protocol:
Step 1: Request the Complete Carrier Field Adjuster Report & Photo Log
Under Florida's Homeowner Claims Bill of Rights (F.S. § 627.7142), you have the statutory right to request free copies of all loss estimates, engineering reports, and photographs relied upon by your insurer within 7 days of your written request. Reviewing the adjuster's raw photo report often reveals that entire roof slopes, valley flashings, or attic rafters were never inspected.
Step 2: Schedule a Certified Forensic Roof Inspection
Before entering mediation or filing a supplemental claim, bring in a state-certified roofing contractor to perform a comprehensive professional roof inspection. At Diversified Roofing Solutions, our inspection team documents:
- Directional Wind Vectors: Mapping damaged slopes against recorded National Weather Service gust directions for your exact zip code in West Palm Beach, Boca Raton, or Hobe Sound.
- Discontinued Material Verification: Identifying dorsal stamp markings on broken concrete or clay tiles (such as discontinued Monier, Lifetile, Pioneer, or Gory profiles) that can no longer be legally interlocked without creating a water dam.
- Code-Required Line Items: Building a carrier-grade itemized scope that includes mandatory Florida Building Code upgrades—including re-nailing the wood deck with 8d ring-shank nails, installing a peel-and-stick secondary water barrier, and replacing corroded valley metal.
Step 3: Submit a Formal Supplemental Package or Request DFS Mediation
Armed with photographic evidence, code citations, and an itemized replacement scope, you can request a formal re-inspection with a senior carrier adjuster. If the carrier still refuses to acknowledge documented storm damage, Florida homeowners can invoke Florida Department of Financial Services (DFS) Property Insurance Mediation (at the insurer's expense) or exercise the policy's Appraisal Clause when the dispute involves the scope and dollar amount of covered repairs.
Protect Your Home and Insurance Eligibility
Whether you are appealing an unjust Florida roof insurance claim denial or evaluating whether a targeted residential roof repair is more cost-effective than filing a claim against a high hurricane deductible, accurate diagnostics make all the difference. You can also model how a code-compliant reroof will slash your future annual premiums by using our interactive Florida Wind Mitigation Insurance Savings Calculator.